第27章貨幣と銀行制度
A Bank’s Balance Sheet銀行の貸借対照表
A balance sheet is an accounting tool that lists assets and liabilities. An asset is something of value that you own and you can use to produce something. For example, you can use the cash you own to pay your tuition. If you own a home, this is also an asset. A liability is a debt or something you owe. Many people borrow money to buy homes. In this case, a home is the asset, but the mortgage is the liability. The net worth is the asset value minus how much is owed (the liability). A bank’s balance sheet operates in much the same way. A bank’s net worth as bank capital. We also refer to a bank has assets such as cash held in its vaults, monies that the bank holds at the Federal Reserve bank (called “reserves”), loans that it makes to customers, and bonds.
英語のヒント
貸借対照表は、資産と負債を一覧にする会計上の道具である。資産とは、所有しており、何かを生み出すために使える価値のあるものである。たとえば、手持ちの現金は授業料の支払いに使える。持ち家も資産である。負債は借金や支払う義務のあるものである。住宅購入のために借入れをする人は多い。この場合、住宅は資産だが、住宅ローンは負債である。純資産は、資産の価値から負債の額を引いたものである。銀行の貸借対照表も、ほぼ同じように機能する。銀行の純資産は銀行資本とも呼ばれる。また銀行には、金庫に保有する現金、連邦準備銀行に保有する資金(「準備」と呼ばれる)、顧客への貸出し、債券などの資産がある。
Figure 27.5 illustrates a hypothetical and simplified balance sheet for the Safe and Secure Bank. Because of the two-column format of the balance sheet, with the T-shape formed by the vertical line down the middle and the horizontal line under “Assets” and “Liabilities,” we sometimes call it a T-account.
英語のヒント
図27.5は、架空のセーフ・アンド・セキュア銀行の単純化した貸借対照表である。貸借対照表は二列の形式をとり、中央の縦線と「資産」「負債」の下の横線がT字を作るため、T字勘定とも呼ばれる。
A Balance Sheet for the Safe and Secure Bankセーフ・アンド・セキュア銀行の貸借対照表
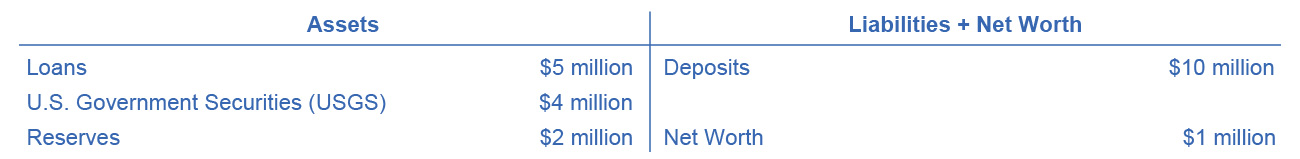

Figure 27.5図 27.5
The “T” in a T-account separates the assets of a firm, on the left, from its liabilities, on the right. All firms use T-accounts, though most are much more complex. For a bank, the assets are the financial instruments that either the bank is holding (its reserves) or those instruments where other parties owe money to the bank—like loans made by the bank and U.S. Government Securities, such as U.S. treasury bonds purchased by the bank. Liabilities are what the bank owes to others. Specifically, the bank owes any deposits made in the bank to those who have made them. The net worth of the bank is the total assets minus total liabilities. Net worth is included on the liabilities side to have the T account balance to zero. For a healthy business, net worth will be positive. For a bankrupt firm, net worth will be negative. In either case, on a bank’s T-account, assets will always equal liabilities plus net worth.
英語のヒント
T字勘定の「T」は、企業の資産を左側、負債を右側に分ける。すべての企業がT字勘定を使うが、その大部分はもっと複雑である。銀行の資産は、銀行が保有する金融上の資産(準備)か、他の当事者が銀行に支払う義務を負う金融商品である。後者には銀行の貸出金や、銀行が購入した米国財務省証券などの米国政府証券がある。負債は銀行が他者に対して負う支払義務である。具体的には、銀行に預けられた預金を預金者に返す義務がある。銀行の純資産は、資産総額から負債総額を引いたものである。T字勘定の差額をゼロにするため、純資産を負債側に記載する。健全な企業の純資産は正で、破綻した企業の純資産は負となる。いずれの場合も、銀行のT字勘定では、資産は常に負債と純資産の合計に等しい。
When bank customers deposit money into a checking account, savings account, or a certificate of deposit, the bank views these deposits as liabilities. After all, the bank owes these deposits to its customers, when the customers wish to withdraw their money. In the example in Figure 27.5, the Safe and Secure Bank holds $10 million in deposits.
英語のヒント
銀行の顧客が当座預金口座、貯蓄口座、譲渡性預金に資金を預けると、銀行はこれを負債とみなす。顧客が引き出したいときには、その預金を返す義務があるからである。図27.5の例では、セーフ・アンド・セキュア銀行は1,000万ドルの預金を預かっている。
Loans are the first category of bank assets in Figure 27.5. Say that a family takes out a 30-year mortgage loan to purchase a house, which means that the borrower will repay the loan over the next 30 years. This loan is clearly an asset from the bank’s perspective, because the borrower has a legal obligation to make payments to the bank over time. However, in practical terms, how can we measure the value of the mortgage loan that the borrower is paying over 30 years in the present? One way of measuring the value of something—whether a loan or anything else—is by estimating what another party in the market is willing to pay for it. Many banks issue home loans, and charge various handling and processing fees for doing so, but then sell the loans to other banks or financial institutions who collect the loan payments. We call the market where financial institutions make loans to borrowers the primary loan market, while the market in which financial institutions buy and sell these loans is the secondary loan market.
英語のヒント
図27.5の銀行資産の最初の項目は貸出金である。ある家族が住宅購入のために30年の住宅ローンを借りたとしよう。これは、借り手が今後30年間にわたって返済することを意味する。借り手には将来にわたって銀行へ支払う法的義務があるので、この貸出しは銀行から見れば明らかに資産である。しかし実際には、借り手が30年間にわたって返済する住宅ローンの価値を、現在どう測ればよいのだろうか。貸出しであれ何であれ、その価値を測る一つの方法は、市場のほかの当事者がいくら払おうとするかを推定することである。多くの銀行は住宅ローンを実行して各種の取扱・事務手数料を徴収するが、その後、返済金を受け取るほかの銀行や金融機関へそのローンを売る。金融機関が借り手に融資する市場を貸出しの発行市場、金融機関がその貸出債権を売買する市場を貸出しの流通市場と呼ぶ。
One key factor that affects what financial institutions are willing to pay for a loan, when they buy it in the secondary loan market, is the perceived riskiness of the loan: that is, given the borrower's characteristics, such as income level and whether the local economy is performing strongly, what proportion of loans of this type will the borrower repay? The greater the risk that a borrower will not repay loan, the less that any financial institution will pay to acquire the loan. Another key factor is to compare the interest rate the financial institution charged on the original loan with the current interest rate in the economy. If the original loan requires the borrower to pay a low interest rate, but current interest rates are relatively high, then a financial institution will pay less to acquire the loan. In contrast, if the original loan requires the borrower to pay a high interest rate, while current interest rates are relatively low, then a financial institution will pay more to acquire the loan. For the Safe and Secure Bank in this example, the total value of its loans if they sold them to other financial institutions in the secondary market is $5 million.
英語のヒント
金融機関が貸出債権を流通市場で買う際に、いくら支払うかに影響する重要な要因の一つが、認識されている貸出しのリスクである。つまり、所得水準や地元経済が好調かどうかなど、借り手の特徴を考慮したとき、この種類の貸出しのうちどの程度が返済されるかである。返済されないリスクが大きいほど、金融機関が貸出債権の取得に支払う金額は少なくなる。もう一つの重要な要因は、元の貸出金利と経済の現在の金利との比較である。元の貸出しで借り手に求められる金利が低く、現在の金利が比較的高ければ、金融機関はその債権の取得に支払う額を減らす。逆に、元の貸出金利が高く、現在の金利が比較的低ければ、より多く支払う。この例のセーフ・アンド・セキュア銀行では、貸出債権を流通市場でほかの金融機関へ売った場合の総価値は500万ドルである。
The second category of bank asset is bonds, which are a common mechanism for borrowing, used by the federal and local government, and also private companies, and nonprofit organizations. A bank takes some of the money it has received in deposits and uses the money to buy bonds—typically bonds issued that the U.S. government issues. Government bonds are low-risk because the government is virtually certain to pay off the bond, albeit at a low rate of interest. These bonds are an asset for banks in the same way that loans are an asset: The bank will receive a stream of payments in the future. In our example, the Safe and Secure Bank holds bonds worth a total value of $4 million.
英語のヒント
銀行資産の第二の種類は債券である。債券は、連邦政府、地方政府、民間企業、非営利団体が一般的に使う借入れの仕組みである。銀行は受け入れた預金の一部を使って債券を買う。通常は米国政府が発行する債券である。国債のリスクが低いのは、金利は低いものの、政府がほぼ確実に償還するためである。債券も貸出金と同じ意味で銀行の資産である。銀行は将来、一連の支払いを受ける。この例では、セーフ・アンド・セキュア銀行は総額400万ドルの債券を保有している。
The final entry under assets is reserves, which is money that the bank keeps on hand, and that it does not lend or invest in bonds—and thus does not lead to interest payments. The Federal Reserve requires that banks keep a certain percentage of depositors’ money on “reserve,” which means either in their vaults or at the Federal Reserve Bank. We call this a reserve requirement. (Monetary Policy and Bank Regulation will explain how the level of these required reserves are one policy tool that governments have to influence bank behavior.) Prior to the financial crisis of 2008–2009, also known as the Great Recession, banks received no interest on the reserves they kept with their regional Federal Reserve bank. This represented an opportunity cost—the foregone interest earned for keeping any excess reserves. Therefore, banks tended to keep only the minimum amount of required reserves. When banks choose to keep only the minimum amount of required reserves (or slightly more than that minimum), in other words when banks are at or slightly above their reserve requirement, we call this limited reserves. When banks choose to keep significantly more than their reserve requirement, they have a large amount of excess reserves. We call this ample reserves. Additionally, banks may also want to keep a certain amount of reserves on hand in excess of what is required. The Safe and Secure Bank is holding $2 million in reserves.
英語のヒント
資産の最後の項目は準備である。これは銀行が手元に置き、貸し出したり債券に投資したりしない資金であり、そのため利息収入を生まない。連邦準備制度は、預金者の資金の一定割合を、金庫内または連邦準備銀行に「準備」として保有するよう銀行に義務づける。これを準備要件と呼ぶ。(「金融政策と銀行規制」では、所要準備の水準が、政府が銀行行動に影響を与える政策手段の一つであることを説明する。)大不況とも呼ばれる2008~2009年の金融危機以前には、銀行が地区連邦準備銀行に置く準備には利息がつかなかった。したがって超過準備を保有すると、得られたはずの利息を放棄する機会費用が生じた。そのため銀行は、所要準備の最低額だけを保有する傾向があった。銀行が所要準備の最低額、またはそれをわずかに上回る額だけを保有する場合、つまり準備要件と同じか、それを少し上回る水準にある場合を、限定的準備と呼ぶ。銀行が準備要件を大幅に上回る準備を保有すると、大量の超過準備をもつことになる。これを潤沢な準備と呼ぶ。さらに銀行は、所要額を上回る一定の準備を手元に置いておきたいと考えることもある。セーフ・アンド・セキュア銀行は200万ドルの準備を保有している。
We define net worth of a bank as its total assets minus its total liabilities. For the Safe and Secure Bank in Figure 27.5, net worth is equal to $1 million; that is, $11 million in assets minus $10 million in liabilities. For a financially healthy bank, the net worth will be positive. If a bank has negative net worth and depositors tried to withdraw their money, the bank would not be able to give all depositors their money.
英語のヒント
銀行の純資産は、資産総額から負債総額を引いたものと定義する。図27.5のセーフ・アンド・セキュア銀行では、資産1,100万ドルから負債1,000万ドルを引き、純資産は100万ドルとなる。財務の健全な銀行では、純資産は正になる。純資産が負の銀行で預金者が引き出しを求めると、銀行はすべての預金者へ資金を返せない。